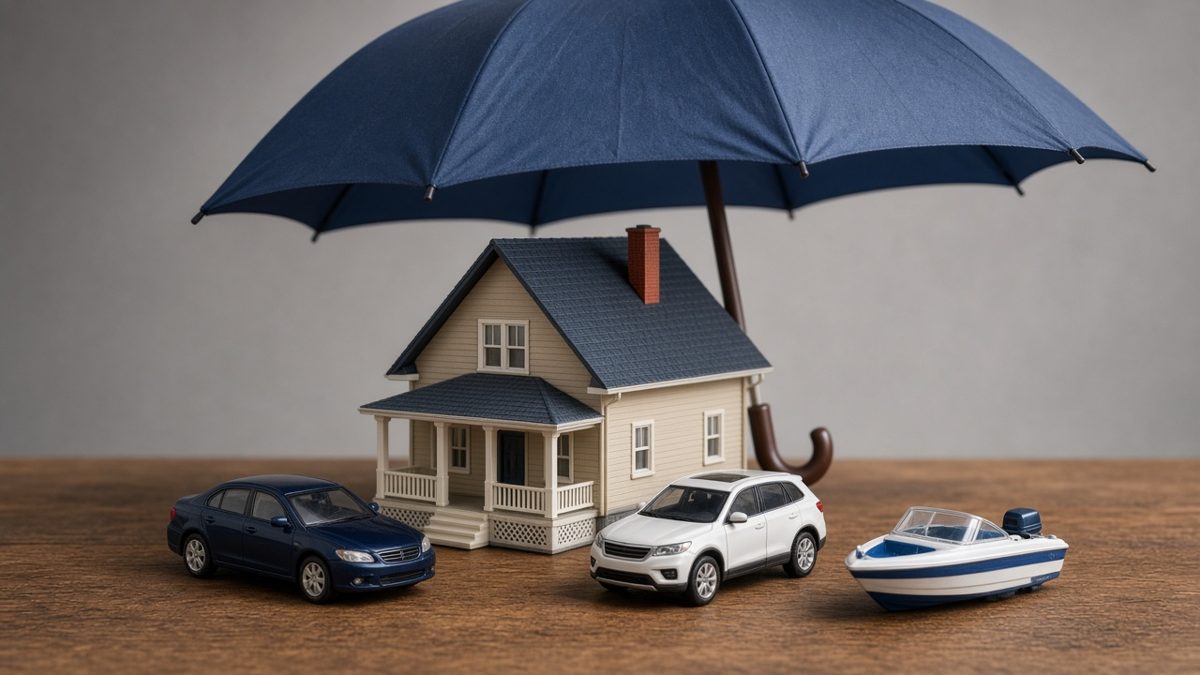
A personal umbrella policy is a layer of liability insurance that sits above your auto, homeowners, renters, and sometimes watercraft policies. When a claim exhausts the limits of those underlying policies, the umbrella pays the excess, up to its own limit. Umbrella insurance is typically sold in increments of $1 million, and for many households it is one of the most cost-effective ways to protect savings, home equity, and future income from a lawsuit.
How an umbrella policy works
Suppose you cause a multi-car accident and a jury awards damages well above your auto liability limit of $250,000 per person. Your auto insurer pays up to its limit, and your umbrella policy pays the remaining amount up to the umbrella limit. Without the umbrella, the injured party could seek the balance from your personal assets.
Umbrellas also often cover claims that your underlying policies do not, sometimes subject to a self-insured retention, which acts like a deductible. Examples commonly include:
- Personal injury. Libel, slander, defamation, false arrest, and invasion of privacy. A negative online review that leads to a defamation lawsuit is a modern example.
- Worldwide coverage. Liability for incidents abroad, such as an accident in a rental car overseas, depending on policy terms.
- Defense costs. Many umbrellas pay legal defense costs in addition to the policy limit, which matters because defending a serious lawsuit can be expensive.
Underlying limit requirements
Insurers require you to carry certain minimum limits on your underlying policies before they will issue an umbrella. Typical requirements look like this:
- Auto liability. Often 250/500/100, or a $300,000 or $500,000 combined single limit.
- Homeowners or renters liability. Commonly $300,000.
- Watercraft or recreational vehicles. Specified limits if you own boats, ATVs, or golf carts.
If your underlying limits fall below the requirement and you have a claim, you may be responsible for the gap between your actual limit and the required one before the umbrella pays. Always confirm that your auto and home policies meet the umbrella insurer’s requirements, especially after changing carriers.
What umbrella insurance costs
Umbrella coverage is relatively inexpensive because it pays only after other policies are exhausted, which is rare. Industry estimates for the first $1 million commonly fall somewhere in the range of a few hundred dollars per year, with each additional million costing less. Pricing depends on the number of drivers and vehicles in your household, teen or young drivers, driving records, properties owned, pools, trampolines, dogs, and boats. Buying the umbrella from the same insurer as your auto and home policies often yields a discount and simplifies claims.
Who should consider an umbrella
Lawsuit risk is not limited to the wealthy. Courts can award damages based on the injuries suffered, not on the defendant’s net worth, and in many states a judgment can lead to wage garnishment for years. Households commonly considering umbrella coverage include:
- Homeowners with significant equity. Equity beyond your state’s homestead exemption may be reachable by creditors.
- Families with teen drivers. Young drivers are statistically more likely to be involved in crashes.
- People with pools, trampolines, or dogs. These raise the risk of injuries to guests.
- Landlords. Owners of rental property face tenant and visitor injury claims, though some umbrellas limit coverage for rental units or require them to be scheduled.
- High earners. Future income can be targeted in a judgment.
- People with public profiles. Volunteers, coaches, and anyone active on social media can face defamation claims.
- Boat owners. Watercraft accidents can cause serious injuries.
How much coverage to buy
A common guideline is to carry umbrella coverage at least equal to your net worth, then add more if you have high future earning potential. Some advisers suggest considering the full amount you could lose, including retirement savings, even though many retirement accounts receive strong protection under federal and state law. ERISA-qualified plans such as 401(k)s are generally protected from most creditors, and IRAs receive bankruptcy protection up to a federally indexed limit, with state law governing outside bankruptcy.
Common exclusions
Umbrella policies are broad but not unlimited. Typical exclusions include:
- Intentional acts. Harm you cause on purpose is not covered.
- Business activities. Liability arising from your business usually requires a commercial umbrella.
- Professional services. Malpractice and errors and omissions require professional liability insurance.
- Your own injuries or property. Umbrellas cover liability to others, not your own losses.
- Contractual liability. Obligations you assume under a contract may be excluded.
- Certain vehicles and aircraft. Some recreational vehicles, aircraft, and large boats are excluded unless scheduled.
- Uninsured motorist coverage. Many umbrellas do not include it, though some insurers offer it as an option.
Umbrella policies and board service
People who serve on nonprofit boards, homeowners association boards, or school committees may face lawsuits tied to board decisions. Personal umbrellas often exclude or limit directors and officers liability. Ask whether the organization carries D&O insurance and whether your umbrella provides any coverage for volunteer board service.
Buying and reviewing an umbrella policy
- List all household members, drivers, vehicles, properties, and recreational vehicles.
- Confirm the umbrella insurer’s underlying limit requirements and adjust your auto and home policies.
- Request quotes for $1 million and $2 million to compare the marginal cost.
- Read the exclusions and definitions of who is an insured, particularly for college students living away and for household members who are not relatives.
- Review the policy each year and after major life changes: a new teen driver, a new property, a pool, or a business started at home.
A note on asset protection strategies
Umbrella insurance is one piece of asset protection. Others include properly structured business entities, adequate professional liability coverage, and state homestead exemptions, which vary dramatically. Florida and Texas, for example, offer generous homestead protection, while some states protect only a small amount of equity. Insurance remains the most straightforward tool because it pays claims and defense costs rather than merely shielding assets after a judgment.
What a claim looks like in practice
When a serious claim arises, you notify both your underlying insurer and your umbrella insurer right away. The underlying insurer usually leads the defense at first, appointing and paying defense counsel. If it appears that damages may exceed underlying limits, the umbrella insurer becomes more involved, sometimes appointing additional counsel and taking part in settlement discussions. Late notice to the umbrella carrier can create coverage disputes, so report any incident that could lead to a large claim, even if you think it will be resolved within your primary limits.
You may also receive a letter from your insurer explaining that a lawsuit seeks damages above your limits and that you may wish to hire your own attorney. This is called an excess letter, and it is a signal that an umbrella would have been valuable or, if you have one, that it may be triggered.
Umbrella insurance for landlords and short-term rentals
Owners of one or two rental homes can often add them to a personal umbrella if each rental has a landlord policy with adequate liability limits. Owners of larger portfolios or properties held in LLCs may need a commercial umbrella instead. If you rent your home on short-term rental platforms, ask your insurer how that activity is treated. Some personal policies exclude or limit coverage for home-sharing, and the platform’s host protection programs have their own terms and exclusions.
Reviewing your household’s risk profile
Before buying, take an honest look at the activities in your household. Do you host large gatherings, have frequent visitors, or employ a nanny or housekeeper? Do family members ride motorcycles, own firearms, or drive for rideshare services? Each of these can affect underlying coverage and umbrella eligibility. Disclosing them up front helps ensure that a claim is not contested later.
Frequently Asked Questions
Does an umbrella cover my teenager driving my car?
Generally yes, if the teen is a listed driver on your auto policy and a resident of your household. Confirm that every driver is disclosed.
Can I buy an umbrella without home insurance?
Yes. Renters can buy umbrella policies, usually with renters liability as one of the underlying policies.
Is umbrella insurance the same as excess liability?
They are similar. An excess policy usually follows the terms of the underlying policy, while an umbrella can be broader and cover some claims the underlying policies exclude.
This article is for general informational purposes only and is not legal, medical, tax, or financial advice. Rules vary by state and change over time; confirm details with the relevant agency or a licensed professional.