Certificates of deposit, or CDs, let you lock in a fixed interest rate for a set term in exchange for keeping your money on deposit. Longer terms often pay more, but tying up all your savings for years can be risky if you need cash. A CD ladder strategy solves that trade-off by splitting your money across CDs that mature at different times. As each CD matures, you get access to cash or can reinvest it at current rates. This guide explains how a CD ladder works, how to build one, and how it compares with other safe savings options.
How certificates of deposit work
A CD is a deposit account with:
- A fixed term, commonly ranging from three months to five years or more
- A fixed interest rate for the term, in most cases
- An early withdrawal penalty if you take money out before maturity
- Federal deposit insurance up to $250,000 per depositor, per insured bank, per ownership category at FDIC-insured banks, with the same coverage at NCUA-insured credit unions
When the CD matures, you usually have a short grace period, often 7 to 10 days, to withdraw the money or change terms. If you do nothing, many banks automatically renew the CD for the same term at the current rate, which may be lower than what you could find elsewhere.
What is a CD ladder?
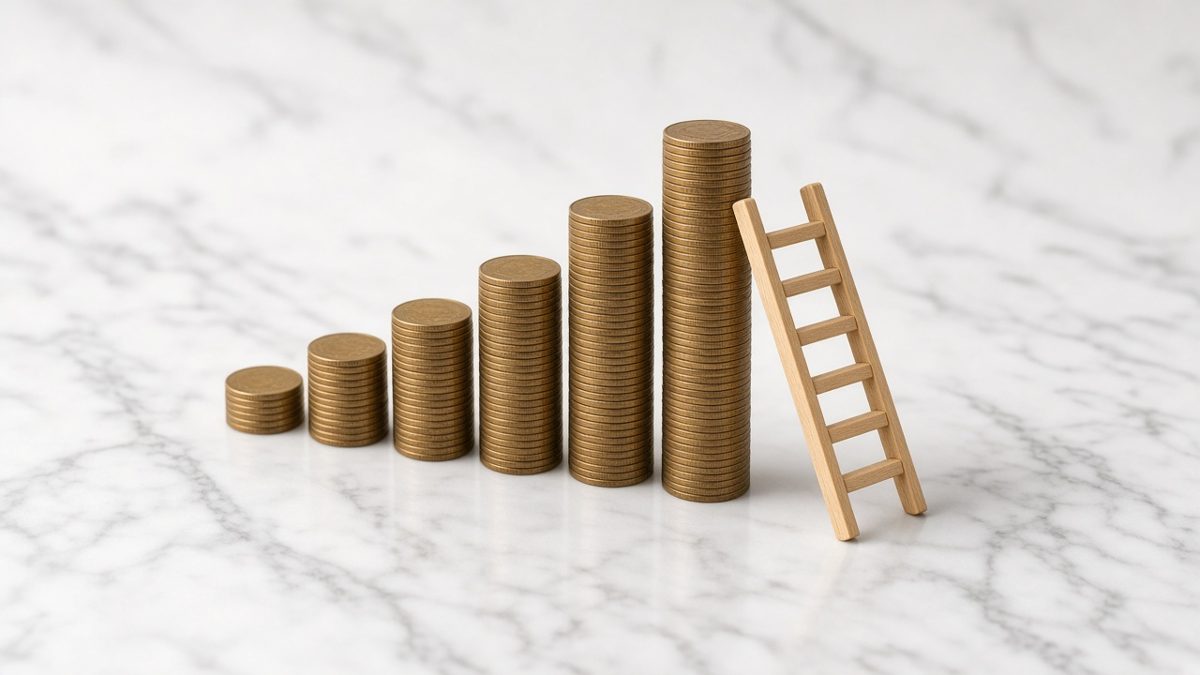
A CD ladder divides your savings into several CDs with staggered maturities. A classic five-year ladder looks like this:
| Rung | Initial term | Amount (example: $25,000 total) |
|---|---|---|
| 1 | 1 year | $5,000 |
| 2 | 2 years | $5,000 |
| 3 | 3 years | $5,000 |
| 4 | 4 years | $5,000 |
| 5 | 5 years | $5,000 |
After one year, the 1-year CD matures. You reinvest it in a new 5-year CD. The next year, the original 2-year CD matures and you do the same. After the first cycle, you own five 5-year CDs, one of which matures every year. You earn rates closer to long-term CD rates while still getting access to part of your money annually.
Benefits of a CD ladder
- Regular liquidity. Part of your money becomes available on a predictable schedule.
- Rate diversification. You are not betting everything on today’s rates. If rates rise, maturing rungs can be reinvested higher. If rates fall, your longer rungs keep earning the older, higher rates for a while.
- Predictable, guaranteed returns. The rate on each CD is fixed, and principal is federally insured within limits.
- Discipline. Money in CDs is less tempting to spend than money in checking.
Drawbacks to consider
- Early withdrawal penalties. Breaking a CD early typically costs a set number of months of interest, and penalties vary widely by bank. In some cases a penalty can reduce principal.
- Inflation risk. Fixed rates may not keep up if inflation rises sharply.
- Opportunity cost. Over long periods, stocks have historically offered higher returns, though with much more risk.
- Administrative work. You need to track maturity dates and make decisions during each grace period.
- Taxes. CD interest is taxable as ordinary income in the year it is credited, even if you do not withdraw it, unless the CD is held in a tax-advantaged account such as an IRA.
How to build a CD ladder step by step
- Decide how much to ladder. Use money you will not need on short notice. Keep your core emergency fund, or at least part of it, in a liquid high-yield savings account.
- Choose the ladder length and spacing. A five-year ladder with annual rungs is classic, but shorter ladders work too. For example, a one-year ladder with CDs at 3, 6, 9, and 12 months gives quarterly access.
- Compare certificate of deposit rates. Check online banks, credit unions, and local banks. Rates vary significantly, and online institutions often pay more.
- Read the early withdrawal penalty terms and minimum deposit requirements for each CD.
- Open the CDs and fund each rung.
- Track maturity dates with calendar reminders a week ahead.
- Reinvest or withdraw as each rung matures, depending on your needs and current rates.
Variations on the strategy
Mini ladder
For short-term goals within a year or two, use shorter terms, such as 3-, 6-, 9-, and 12-month CDs. This can work well for a planned purchase like a car or a tuition payment.
Barbell strategy
Put part of your money in short-term CDs and part in long-term CDs, skipping the middle. This keeps some liquidity while capturing longer-term rates.
Bullet strategy
Buy CDs at different times that all mature around the same date, useful when you know exactly when you need a lump sum, such as a home down payment.
Including a no-penalty CD
A no-penalty CD lets you withdraw without a fee after a short initial period, though rates are often slightly lower. Using one as a rung can add flexibility.
Bank CDs vs brokered CDs
Brokered CDs are issued by banks but bought and sold through brokerage accounts. They can make it easy to build a ladder across many banks from one account.
| Feature | Bank CD | Brokered CD |
|---|---|---|
| Where you buy | Directly from a bank or credit union | Through a brokerage firm |
| Early access | Withdraw with a penalty | Sell on the secondary market; price may be higher or lower than what you paid |
| Insurance | FDIC/NCUA within limits | FDIC within limits at the issuing bank |
| Callable features | Rare | Some brokered CDs are callable, meaning the bank can redeem them early |
| Compounding | Often compounds | Often pays simple interest |
If you choose brokered CDs, check whether a CD is callable, because a callable CD may be redeemed when rates fall, cutting your rate advantage short.
CD ladder vs other safe options
| Option | Rate type | Liquidity | Notes |
|---|---|---|---|
| High-yield savings | Variable | Daily | Best for emergency funds |
| CD ladder | Fixed per rung | Periodic | Higher fixed rates with planned access |
| Treasury ladder | Fixed per bill or note | Periodic or sell anytime | Interest exempt from state and local income tax |
| Money market fund | Variable | Daily | Not FDIC insured |
| I bonds | Fixed plus inflation rate | Locked for 12 months; penalty before 5 years | Purchase limits apply |
A Treasury ladder built from Treasury bills and notes works on the same principle and may yield more after taxes for people in high-tax states, because Treasury interest is exempt from state and local income tax.
Who should use a CD ladder?
A CD ladder may make sense if you:
- Have savings beyond your emergency fund that you want to keep safe
- Are saving for goals one to five years away
- Are retired or near retirement and want predictable income from part of your portfolio
- Value guaranteed returns over potential market gains
It may not suit money you could need at any moment or long-term retirement savings that need growth over decades.
Related reading: How to Improve Your Credit Score: A Practical Step-by-Step Plan.
Frequently Asked Questions
How much money do I need to start a CD ladder?
Many banks have low or no minimum deposits for CDs, so you can start a ladder with a few thousand dollars or less. Some CDs require higher minimums for top rates.
What happens if I need money before a CD matures?
You can usually withdraw early but will pay an early withdrawal penalty, often several months of interest. With brokered CDs, you would sell on the secondary market at the current price.
Are CDs safe?
CDs at FDIC-insured banks or NCUA-insured credit unions are protected up to $250,000 per depositor, per institution, per ownership category.
Is a CD ladder better than a high-yield savings account?
They serve different purposes. Savings accounts offer full liquidity with variable rates, while a ladder locks in fixed rates with scheduled access. Many people use both.
How is CD interest taxed?
CD interest is generally taxed as ordinary income in the year it is earned, and banks report it on Form 1099-INT. CDs held in an IRA follow IRA tax rules.
This article is for general informational purposes only and is not legal, medical, tax, or financial advice. Rules vary by state and change over time; confirm details with the relevant agency or a licensed professional.