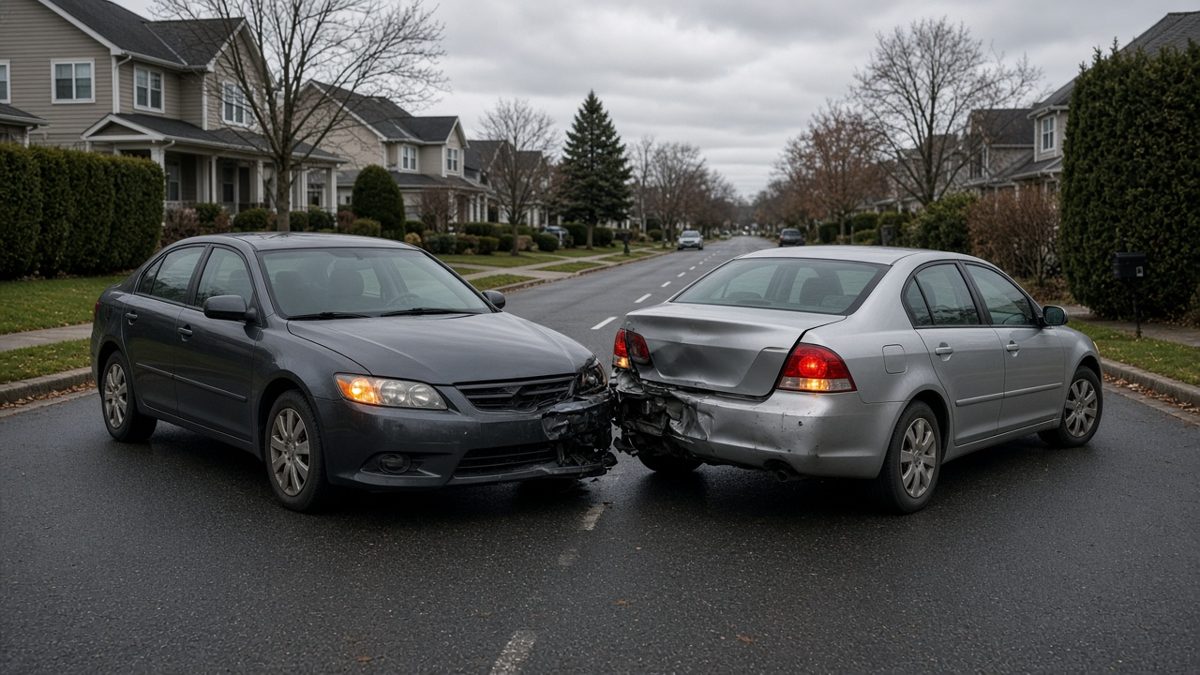
A car accident is stressful and disorienting, even when it is minor. Yet the decisions you make at the scene and in the following days can affect your health, your insurance claim, and any legal rights you may have. This guide walks through what to do after a car accident in the United States, step by step, so you can protect yourself without having to think through everything in the moment.
Important: This article is for informational purposes only and is not legal advice. Traffic and insurance laws differ by state. For guidance on your situation, speak with a licensed attorney or your insurance company.
At the Scene: The First Priorities
1. Check for Injuries and Call 911 If Needed
Check yourself and your passengers first. If anyone is hurt, call 911 immediately. Do not move someone with a possible neck or back injury unless they are in immediate danger, such as from fire. Even if injuries seem minor, adrenaline can mask pain, so consider being evaluated.
2. Move to Safety
If the vehicles can be driven and no one is injured, many states require or encourage drivers to move out of traffic lanes to a safe spot nearby. Turn on hazard lights. If the cars cannot be moved, get yourself and your passengers to a safe location away from traffic.
3. Call the Police
Calling the police is often a good idea even for minor crashes. Many states require reporting accidents that involve injuries, deaths, or property damage above a certain dollar threshold. A police report creates an independent record that insurers frequently rely on. Ask the officer how you can obtain a copy and write down the report number.
4. Exchange Information
Collect the following from every driver involved:
- Full name and contact information
- Driver’s license number
- Insurance company and policy number
- Vehicle make, model, color, and license plate number
- Vehicle owner’s name, if different from the driver
5. Document the Scene
Use your phone to take photos and video of:
- Damage to all vehicles from multiple angles
- The position of vehicles before they are moved, if safe to photograph
- Skid marks, debris, road conditions, traffic signals, and signs
- Weather and lighting conditions
- Visible injuries
Get names and phone numbers of witnesses. Independent witnesses can be valuable if fault is disputed.
6. Be Careful What You Say
Be polite, but avoid admitting fault or speculating about what happened. Statements like “I’m sorry, I didn’t see you” can be used later to argue you were responsible. Stick to facts when speaking with the police and other drivers.
In the Days After the Accident
Get a Medical Evaluation
Some injuries, such as whiplash, concussions, and internal injuries, may not show symptoms right away. Seeing a doctor promptly protects your health and documents a link between the crash and your injuries. Follow your treatment plan; gaps in care are commonly used by insurers to argue an injury was not serious or was caused by something else.
Notify Your Insurance Company
Most auto policies require you to report an accident promptly, even if you were not at fault. Give the basic facts. You can usually notify your insurer and still decide later whether to pursue a claim against the other driver.
Be Cautious With the Other Driver’s Insurer
The other driver’s insurer may contact you quickly and ask for a recorded statement. You are generally not obligated to provide one. Their adjuster’s job is to minimize what their company pays. Consider speaking with an attorney before giving a statement or signing any medical authorizations or releases.
Keep Organized Records
Create a folder, paper or digital, for:
- The police report
- Photos and videos
- Medical records and bills
- Receipts for prescriptions, rentals, and towing
- Records of missed work and lost income
- All correspondence with insurers
A simple journal of your symptoms and how they affect daily activities can help document pain and suffering.
Understanding Fault vs. No-Fault States
How your injuries get paid for depends on where the accident happened.
| System | How It Works |
|---|---|
| At-fault (tort) states | The at-fault driver’s liability insurance pays for others’ injuries and damage |
| No-fault states | Your own personal injury protection (PIP) pays your medical bills and some lost wages regardless of fault; suing the other driver is limited unless injuries meet a threshold |
| Choice states | Drivers may choose between no-fault and traditional tort coverage |
A minority of states use a no-fault system for injuries. Property damage to vehicles is generally handled on a fault basis even in no-fault states. Check your state’s rules or ask your insurer which applies.
Filing a Car Accident Claim
Property Damage Claims
You generally have two options for vehicle repairs:
- File with the other driver’s insurer if they were at fault. You avoid paying your deductible, but the process may be slower if they dispute liability.
- File with your own insurer under collision coverage. You will usually pay your deductible, but your insurer may seek reimbursement from the at-fault driver’s insurer and refund your deductible if successful.
If your car is declared a total loss, the insurer typically pays its actual cash value, which reflects depreciation. You may negotiate the valuation using comparable vehicle listings.
Injury Claims
If you were injured, your claim may cover medical expenses, lost wages, and in many cases pain and suffering. In no-fault states, you will usually start with your own PIP coverage.
When the Other Driver Is Uninsured
If the at-fault driver has no insurance or too little, your own uninsured/underinsured motorist coverage may pay. Some states require this coverage; in others it is optional. Review your policy to see what you carry.
Hit-and-Run Accidents
Report a hit-and-run to the police immediately and note any detail you can recall about the vehicle. Your uninsured motorist coverage, and collision coverage for your vehicle, may apply.
Deadlines You Need to Know
- Insurance notice: Your policy may require prompt notice of an accident.
- State accident reports: Some states require drivers to file a report with the DMV or another agency within a short period, sometimes as little as several days, when damage or injury exceeds a threshold.
- Statute of limitations: Every state limits how long you have to file a lawsuit for injuries or property damage. Deadlines vary by state and claim type, and claims against government entities often have shorter notice requirements.
When Should You Hire a Lawyer?
You may be able to handle a minor property-damage-only claim yourself. Consider consulting a car accident attorney if:
- You or a passenger suffered significant injuries
- Fault is disputed or multiple vehicles are involved
- The insurer denies your claim or makes a low offer
- A commercial vehicle, rideshare, or government vehicle was involved
- Your injuries required surgery or will need long-term care
Many car accident lawyers offer free consultations and work on a contingency fee.
Mistakes to Avoid After a Crash
- Leaving the scene before exchanging information, which can be a crime
- Admitting fault or apologizing in a way that implies blame
- Skipping medical care or stopping treatment early
- Accepting a quick settlement before you understand your injuries
- Posting about the accident on social media
- Signing documents from the other insurer without review
Keep a Simple Accident Checklist in Your Car
It is easy to forget important steps when you are shaken. Many drivers keep a small checklist in the glove compartment, along with a pen, a copy of their insurance card, and their vehicle registration. Some also keep a disposable camera or a phone charger in case their phone battery is low. Having emergency items such as reflective triangles, a flashlight, and a basic first aid kit can also make the scene safer while you wait for help.
Frequently Asked Questions
Do I have to call the police after a minor accident?
It depends on your state and the circumstances. Many states require a report when there is injury, death, or damage above a set amount. Even when not required, a police report can help support your claim.
Should I see a doctor if I feel fine?
It is often wise. Some injuries do not show symptoms for hours or days, and a prompt exam documents the connection between the crash and any injury.
Will my insurance rates go up after an accident?
If you were at fault, your premium may increase at renewal. Not-at-fault accidents affect rates less often, though practices vary by insurer and state.
What if the other driver doesn’t have insurance?
Your uninsured motorist coverage may pay for your injuries, and your collision coverage can pay for vehicle repairs, subject to your deductible.
How long do I have to file a car accident claim?
Insurance policies require prompt notice, and state statutes of limitations set the deadline for lawsuits. These deadlines vary, so check your state’s rules early.
This article is for general informational purposes only and is not legal, medical, tax, or financial advice. Rules vary by state and change over time; confirm details with the relevant agency or a licensed professional.