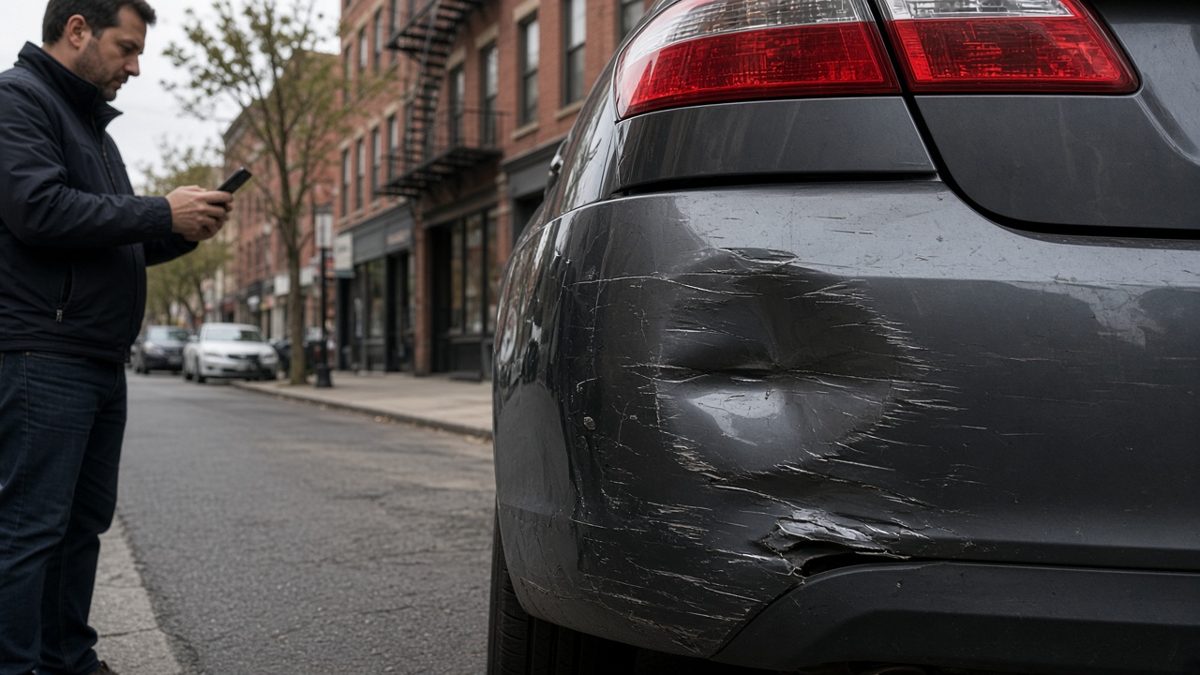
Most car insurance protects other people from you. Uninsured motorist (UM) and underinsured motorist (UIM) coverage does the opposite: it protects you and your passengers when someone else causes a crash and cannot pay. Industry research groups such as the Insurance Research Council have long estimated that a meaningful share of US drivers, roughly one in seven or eight nationally and far more in some states, drive without insurance. Many insured drivers also carry only the legal minimum, which may cover a fraction of a serious injury.
The two types of coverage
Uninsured motorist coverage pays when the at-fault driver has no liability insurance at all. In most states it also applies to hit-and-run crashes where the other driver is never identified, although some states require physical contact with the other vehicle or independent witnesses for hit-and-run claims.
Underinsured motorist coverage pays when the at-fault driver has insurance, but not enough to cover your damages. For example, if your medical bills and lost wages total $90,000 and the other driver carries a $25,000 bodily injury limit, UIM can fill some or all of the remaining gap up to your own UIM limit.
Each comes in two parts:
- Bodily injury (UMBI/UIMBI). Medical bills, lost income, and pain and suffering for you and your passengers.
- Property damage (UMPD). Repairs to your car. Not every state offers UMPD, and where it is offered it may carry a deductible. If you already have collision coverage, UMPD may mainly help you avoid paying your collision deductible.
How state rules differ
States handle UM and UIM in three broad ways:
- Mandatory. A number of states require drivers to carry UM coverage, and some require UIM as well. Examples have included Illinois, Maryland, Minnesota, New York, and others.
- Must be offered. Many states require insurers to include UM/UIM unless you reject it in writing. If you signed a rejection form when you bought the policy, you may not have this coverage, so check your declarations page.
- Optional. In the remaining states, you can add it if you choose.
States also differ in how UIM is calculated. In “limits-less-limits” states, your UIM limit is reduced by the at-fault driver’s liability coverage. In “excess” or “add-on” states, UIM stacks on top of whatever the at-fault driver’s policy pays. The difference can be substantial, so ask your agent which approach your state uses.
Stacking
Some states allow you to “stack” UM coverage, combining limits across multiple vehicles on your policy or across multiple policies. If you insure three cars with $100,000 of stacked UM each, you may have access to $300,000. Stacking typically costs more and is not permitted everywhere. Pennsylvania, for instance, lets drivers choose stacked or unstacked coverage and requires a written waiver to decline stacking.
Why your health insurance is not a full substitute
People sometimes skip UM because they already have health insurance. Health coverage pays medical bills, subject to deductibles and networks, but it does not replace lost wages, compensate for pain and suffering, or cover a passenger who lacks insurance. Health plans may also seek reimbursement, called subrogation, from any settlement you later receive. UM/UIM fills those gaps.
Similarly, disability insurance may replace part of your income, but it rarely covers non-economic damages.
How a UM or UIM claim works
A UM claim is filed with your own insurer, but legally your insurer steps into the shoes of the at-fault driver. That means the company evaluates fault and damages much as the other driver’s insurer would, and it may dispute the value of your claim. Practical steps include:
- Call the police and get a report number, especially in hit-and-run cases.
- Photograph the scene, vehicles, and injuries.
- Notify your insurer promptly. Policies set notice deadlines.
- For UIM claims, many policies require you to get your insurer’s consent before accepting a settlement from the at-fault driver’s insurer, so that your insurer can preserve its subrogation rights. Settling without consent can jeopardize your UIM claim.
- Keep records of medical treatment, missed work, and out-of-pocket costs.
Many UM policies include arbitration clauses for disputes over the amount of damages. Because the process is adversarial, some people consult a personal injury attorney for serious injury claims.
Choosing your limits
A common recommendation is to match your UM/UIM bodily injury limits to your own liability limits. If you carry 100/300 liability, consider 100/300 UM/UIM. Some insurers do not let you buy UM limits higher than your liability limits. The cost of UM/UIM is generally modest compared with the overall premium, though it is higher in states with many uninsured drivers or high claim costs.
If you carry an umbrella policy, check whether it includes uninsured motorist coverage. Many umbrellas exclude it unless you add a specific endorsement, and some insurers do not offer it at all.
Who benefits the most
- Drivers who commute long distances or drive in dense urban areas.
- Families who often drive children or other passengers.
- Motorcyclists, pedestrians, and cyclists. In many states, UM coverage on your auto policy can apply when you are struck as a pedestrian or cyclist.
- People without strong disability or sick-leave benefits through work.
A realistic example of how the gap appears
Imagine a driver stopped at a red light who is rear-ended by a car traveling at highway speed. The injured driver needs emergency care, imaging, a short hospital stay, and several months of physical therapy, and misses work during recovery. The at-fault driver carries only the state minimum bodily injury limit. Once medical bills, lost wages, and the non-economic impact of the injury are added together, the total can easily exceed that minimum. Without UIM, the injured driver’s remaining option is to sue the at-fault driver personally, which may produce little if that person has few assets. With UIM, the injured driver’s own policy can step in for the difference up to its limit.
This scenario is illustrative rather than drawn from any specific case, but it reflects why consumer advocates and many state insurance departments encourage drivers to consider UIM.
Reviewing your current policy
Pull up your declarations page and look for lines labeled uninsured motorist bodily injury, underinsured motorist bodily injury, and uninsured motorist property damage. Note the limits and whether coverage is stacked. If you see nothing, look for a signed rejection form in your policy documents. You can usually add or raise UM/UIM at any time, effective from the date of the change, but coverage does not apply retroactively to a crash that already happened. Make the change before you need it.
Interaction with PIP and MedPay
In no-fault states, your personal injury protection pays first for your medical bills and lost wages regardless of fault. UM/UIM then generally applies to damages beyond PIP, including pain and suffering if you meet your state’s threshold for stepping outside the no-fault system. In other states, medical payments coverage can pay initial bills quickly, with UM/UIM addressing the larger claim.
Related reading: How State Minimum Auto Insurance Requirements Actually Work in the US.
Frequently Asked Questions
Will a UM claim raise my rates?
In many states, insurers are restricted from surcharging you for a not-at-fault UM claim, but rules vary. Ask your insurer or check with your state department of insurance.
Does UM cover me in someone else’s car?
UM bodily injury coverage often follows you as a person, so it may apply as a passenger in another vehicle, usually after that vehicle’s own coverage. Policy language controls.
Is there a deadline for a UM claim?
Yes. Policies set notice requirements, and state statutes of limitations or contract terms limit how long you have to pursue a claim. Do not wait to report a crash.
This article is for general informational purposes only and is not legal, medical, tax, or financial advice. Rules vary by state and change over time; confirm details with the relevant agency or a licensed professional.